Chipmakers and AI Stocks Lead a Sweeping Rally
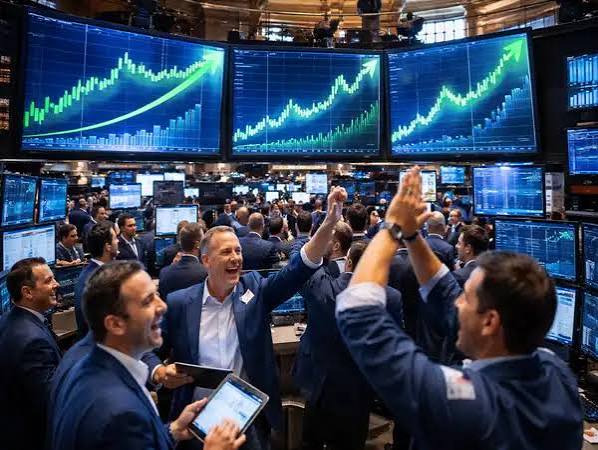
Wall Street delivered its strongest single-day performance in weeks, with technology shares leading a broad-based surge that pushed the Nasdaq Composite to a fresh all-time closing high. The rally was fueled by outsized gains in semiconductor and artificial intelligence-linked names, several of which posted their best one-day moves in more than a year.
The Nasdaq Composite climbed more than two percent, marking its strongest session since early August, while the S&P 500 advanced roughly one and a half percent, also its best day in over a month. The Dow Jones Industrial Average added more than 360 points. Nine of eleven market sectors finished higher, with technology, which accounts for roughly forty percent of total market capitalization, doing the heaviest lifting.
AMD Joins the Trillion-Dollar Club
Among the day’s standout performers was Advanced Micro Devices, whose shares surged sharply enough to push the chipmaker’s market valuation above one trillion dollars for the first time in its history. The milestone places AMD alongside a small handful of companies that have ever reached that threshold, reflecting investor enthusiasm around demand for high-performance computing chips used to power artificial intelligence workloads.
Intel also posted double-digit percentage gains, while ARM Holdings saw an even sharper spike, reflecting a broader wave of optimism across the chip sector. Analysts pointed to recent signals from major cloud infrastructure providers indicating plans to raise pricing on services built around chips from both AMD and Intel, a development some investors interpreted as evidence of continued strong demand despite ongoing questions about the sustainability of AI-related capital spending.
Social media giant Meta Platforms also featured prominently in the rally, jumping more than ten percent in what several market strategists described as its best single trading day in over a year. The move followed reports of encouraging early performance from the company’s newly deployed AI agent products, feeding into a broader narrative that practical, revenue-generating AI applications are beginning to materialize beyond the investment and infrastructure-buildout phase that has dominated headlines for the past two years.
Oil Prices Tumble on Diplomatic Hopes
The rally in equities coincided with a steep decline in crude oil prices after a report from a Japanese wire service suggested Iran had floated the possibility of reopening the Strait of Hormuz within roughly a week. Although the claim relied on a single, unverified source, it was enough to send West Texas Intermediate crude tumbling by more than four percent, while Brent crude also posted a sizable decline.
The Strait of Hormuz remains one of the world’s most strategically important shipping corridors, carrying a substantial share of global seaborne oil exports. Any credible signal of reduced tension in the region tends to ease pressure on energy markets almost immediately, and Monday’s session was no exception. Lower oil prices, in turn, eased inflation concerns among investors, feeding into a broader risk-on mood that lifted equities and pulled down government bond yields simultaneously.
Bond Yields Retreat as Investors Reassess Risk
Treasury yields fell alongside the rally in stocks, with the benchmark ten-year yield dropping below the psychologically significant five percent threshold. That decline reversed some of the upward pressure yields had faced following the Federal Reserve’s recent decision to raise interest rates for the first time since 2023, a move that had initially unsettled fixed-income markets.
European government bonds also saw yield movements tied to the shifting oil and geopolitical backdrop, with yields on French, German and British debt reflecting investors’ recalibrated expectations for inflation and monetary policy across the region.
A Fragile but Welcome Reprieve
Despite the enthusiasm, several market strategists cautioned that the rally’s foundations remain sensitive to fast-moving geopolitical developments. The unverified nature of the Iran shipping report means sentiment could reverse quickly if diplomatic progress stalls or is contradicted by official channels. Still, for a market that had spent much of the prior week grinding through a string of losing sessions, the rebound offered a meaningful, if potentially temporary, sense of relief.
With major earnings reports due later in the week from companies including AutoZone, KB Home, Cintas and General Mills, investors are likely to keep a close eye on whether corporate results can sustain the momentum generated by Monday’s dramatic session, or whether renewed volatility around oil and interest-rate policy will reassert itself in the days ahead.
